What is the Difference Between Savings Account and Current Account?
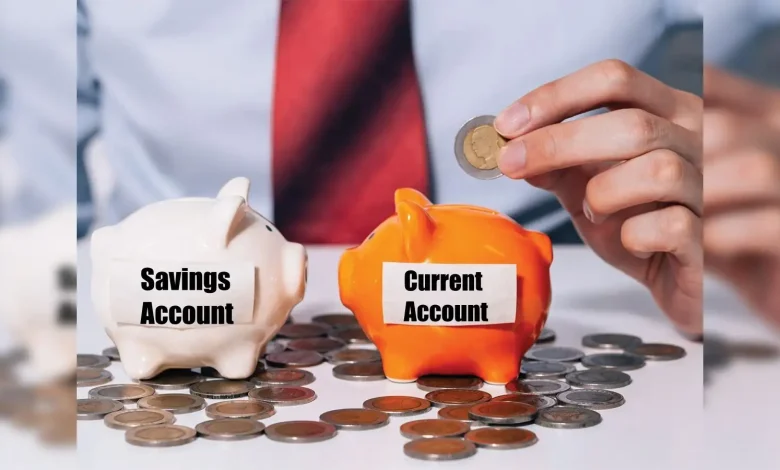
Understanding the difference between a savings account and a current account is a key part of managing your finances effectively. While a savings account is ideal for individuals looking to grow their personal funds, a current account is designed for frequent transactions, typically used by businesses. Knowing how each works can help you choose the right account for your financial needs.
What is a Savings Account?
A savings account is a basic bank account designed for individuals who want to securely store their surplus funds while earning interest over time. It serves as a foundation for building financial discipline and planning for future expenses. Key features of a savings account include:
- Interest income: Your funds increase through interest accounted by the bank.
- Restricted transactions: Banks may cap the number of free withdrawals or transfers per month, especially at branches.
- Simple access: Withdraw funds at any time through ATMs, net banking, or cheques.
- Ideal for: Working professionals, students, homemakers, and retirees who wish to save and cover daily expenses.
A savings account is an ideal option if you want to save for definite goals, a rainy day, or create a buffer against monthly expenses. It helps build a habit of saving and pays you interest for your foresight.
What is a Current Account?
A current account is typically used by businesses, traders, companies, and professionals who need to carry out frequent and high-volume transactions. Unlike savings accounts, current accounts usually do not earn interest but offer greater flexibility for deposits and withdrawals. Here are some key features of a current account:
- Unlimited transactions: Conduct as many deposits and withdrawals as your business needs, with no cap on frequency.
- No interest or very low interest: The main focus is on liquidity and ease of operations, not earning interest.
- Cheque/draft facility: Designed for smooth vendor payments, supplier transactions, and customer dealings.
- Suitable for: Business owners, professionals, companies, and institutions handling a large number of daily transactions.
A current account prioritizes operational efficiency and is essential for anyone running a business or managing operational funds.
Key Differences: Current vs Savings Account
Understanding current vs savings account comes down to analysing their core purposes, features, and benefits. Here’s a summary for easy comparison:
| Feature | Savings Account | Current Account |
| Primary Users | Individuals, families | Businesses, firms, professionals |
| Transactions Limit | Limited per month | Unlimited |
| Interest | Earns interest | Usually no interest |
| Minimum Balance | Generally low | Often higher |
| Overdraft Facility | Rare, usually not offered | Commonly available |
| Objective | Save money, earn interest | Manage daily business transactions |
| Cheque/Online Banking | Available | Available, with enhanced features |
| Penalty for Overuse | Yes, for exceeding limits | Usually none |
Benefits of a Savings Account
Below are some of the benefits you enjoy when you open savings account:
- Earn passive income: Accumulate interest on your deposits with minimal effort.
- High liquidity: Withdraw your money without hassle whenever needed.
- Safe and secure: Keep your funds protected against loss or theft.
- Tailored account types: Options for minors, women, as well as pensioners.
- Building credit history: Using a savings account responsibly is the first step toward qualifying for future financial products.
If you’re aiming for steady growth and easy access to your funds, a savings account is an ideal pick.
Advantages of a Current Account
A current account offers several features that make it well-suited for businesses and professionals who handle frequent or high-value transactions:
- Operational convenience: No restriction on daily transactions, supporting bulk payments, payroll, and vendor management.
- Ease of business transactions: Safely carry out payments and collections with cheques, drafts, and digital transfers.
- Overdraft protection: Certain accounts have overdraft facilities for minor transient needs (generally with agreement).
- Business credibility: Suppliers and associates want to deal with those who conduct business via current accounts since they are more accountable.
A current account makes business more efficient and separates personal and business finances in a clear manner.
Which Account is Right for You?
What type of account to choose based on your unique financial and personal situation? Let’s have a look below:
- For households and individuals: Select a savings account to promote systematic saving and realize steady growth through interest.
- For professionals and companies: Select a current account for smooth day-to-day transactions and professional money management.
- For side-gigs and freelancers: If you get paid regularly, a current account keeps business funds separate from personal money.
Conclusion
Deciding between a savings account and a current account depends on your financial needs. If your goal is to build savings, a savings account is the better fit. If you need to manage frequent or high-volume transactions, a current account is more suitable. Both play important roles in personal and business banking, and choosing the right one can make money management easier and more efficient.